Australia’s real-time payments revolution is accelerating, with the New Payments Platform accounting for more than 70% of new account-to-account transaction growth. Yet the country’s decades-old banking infrastructure still carries most of the money, raising important questions about how businesses modernise payments without leaving existing systems behind.
Australia moved an extraordinary $21.26 trillion between bank accounts in the 12 months to July 2026, across more than 5.35 billion transactions.
That’s an almost unimaginable amount of money flowing through the financial system. But perhaps the most interesting finding isn’t how much Australians are moving. It’s how they’re moving it.
According to Australian payments technology company Zepto’s newly released 2026 Account-to-Account (A2A) Payments Index, the New Payments Platform (NPP) accounted for 71% of the growth in A2A transaction volumes over the reporting period.
The NPP, which underpins services including Osko, PayID and PayTo, now handles 37% of Australia’s account-to-account transactions.
Yet the older Bulk Electronic Clearing System (BECS), which businesses have relied upon for decades to process direct debits, payroll and other payments, still carries a remarkable 86% of the total value transferred.
In other words, Australia’s payments revolution isn’t a straightforward story of new technology replacing old technology.
Both are growing, and businesses increasingly need to understand where each fits.
The future has arrived, but the past is still processing payments
The figures tell a fascinating story. In the year to July 2026, the NPP processed 1.99 billion transactions worth $2.84 trillion. Transaction volumes increased 11.9% year-on-year, while the value of those transactions surged 26%. Meanwhile, BECS continued processing 3.36 billion transactions worth approximately $18.4 trillion.
This data challenges the assumption that modernising Australia’s payments infrastructure is simply a matter of moving everything onto the NPP.
The industry previously anticipated retiring BECS, but that timetable has been abandoned. Businesses are consequently facing a more complicated decision: rather than asking when they must migrate, they need to determine which payment workloads make sense on which infrastructure.
A business processing large batches of established supplier payments may have different requirements from an online marketplace that needs to pay a seller immediately, or a payroll system that must deliver wages and superannuation contributions reliably.
Real-time payments can offer advantages in speed, visibility, and integration, but those benefits need to be considered alongside cost, operational requirements and existing systems.
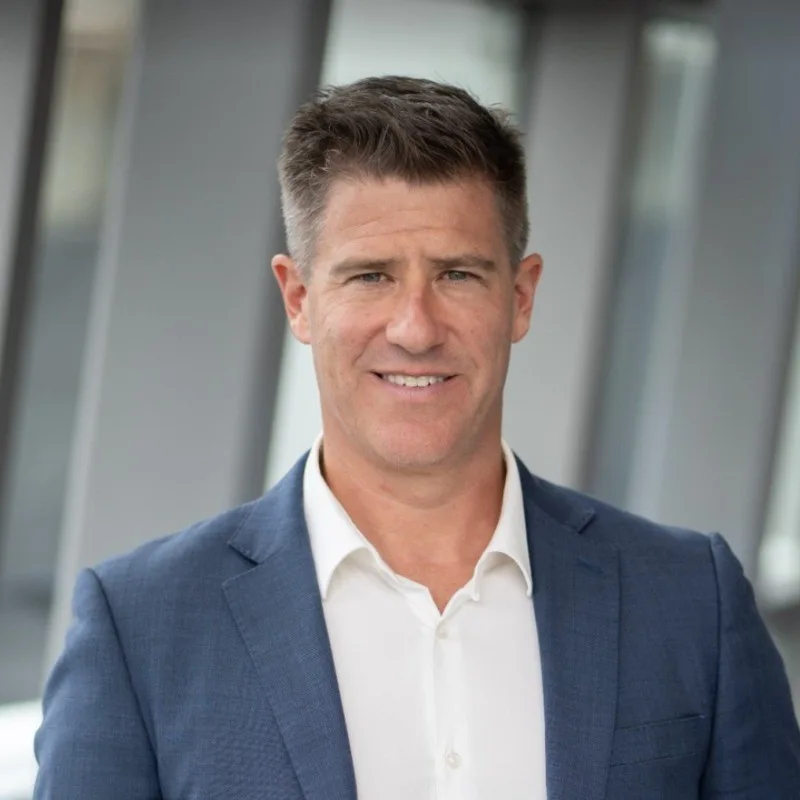
Zepto CEO and co-founder Matt Cheers (pictured) believes the industry has reached a turning point.
“Australia now has a clear vision for A2A payments. But a vision alone does not move a payroll file, resolve a failed supplier payment or make a…
Read More: Real-time payments are booming, so why is Australia’s old banking system
