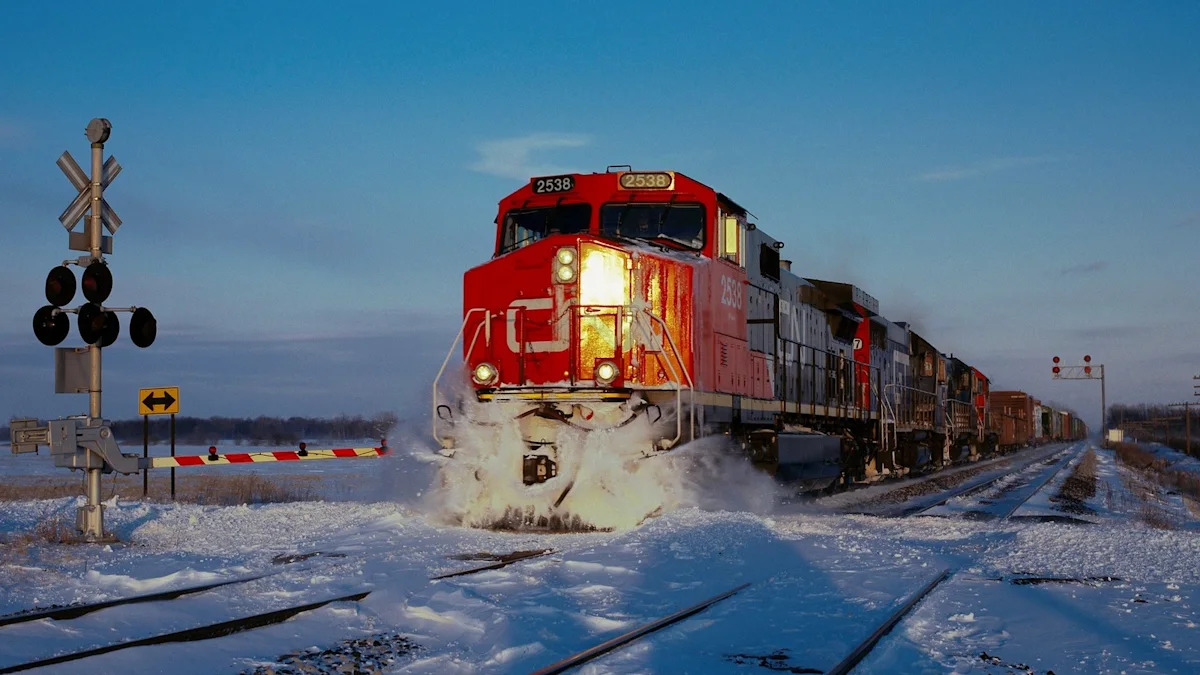
Canadian National Railway stock closed Q3 earnings day at CA$172.81, roughly flat over the past week and modestly ahead over the past month, even as the headline story sat in the income statement. The railway just posted Q3 2026 basic earnings per share of CA$2.00 on CA$4.77b of revenue, with net income of CA$1.21b, and the share price reaction barely flickered.
For short term traders that might look underwhelming. For anyone thinking in years, not days, the more important question now is how those profits, margins and cash generation stack up against the current valuation and multi year earnings forecasts.
Love Canadian National Railway’s steady profits but concerned the muted share price reaction means you are not being paid enough for the patience? Compare it with peers that combine earnings power and resilient balance sheets using our list of solid balance sheet and fundamentals stocks (6 results)
Q3 2026 Earnings Summary
Revenue (Q3 2026 vs. Q3 2025): CA$4,771m vs. CA$4,165m (up about 15%)
Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): CA$1,209m vs. CA$1,139m (up about 6%)
Basic EPS (Q3 2026 vs. Q3 2025): CA$2.00 vs. CA$1.83 (up about 9%)
Net Profit Margin (Trailing 12 Months vs. Prior Year): 26.4% vs. 26.9% (slight margin compression)
Earnings tell you how Canadian National Railway performed on paper in Q3 2026, but the cash flowing through the business is what many valuation focused investors watch most closely. When you compare Canadian National Railway’s cash flows with its current share price, the stock could be a clear 17% overvalued.

Canadian National Railway: Testing The Growth Engine
The bullish story hangs on Canadian National Railway turning Western corridor spend and Fast Track into durable volume and cost wins.
“The main thing that has to go right is that Canadian National Railway successfully turns Western Canada capacity investments, new commercial agreements and Fast Track savings into durable volume growth and lower unit costs.”
Q3 shows important but partial progress. Revenue ton miles rose 4% and grain and fertilizer volumes climbed double digits, which lines up with the Western capacity bet. The adjusted operating ratio improved 40 bps and Fast Track savings reached roughly US$120m year to date, along with record fuel efficiency, which backs the unit cost ambition.
CNR Risk Check: Concentration And Execution Pressure
The bear case questions whether growth is too reliant on a narrow set of flows and projects.
“However, the evidence so far focuses mainly on grain and select energy volumes. If other segments do not contribute meaningfully, then overall free cash flow and earnings growth could fall short of what the valuation assumes.”
Read More: Canadian National Railway (TSX:CNR) Stock Faces A Q3 Earnings Valuation
