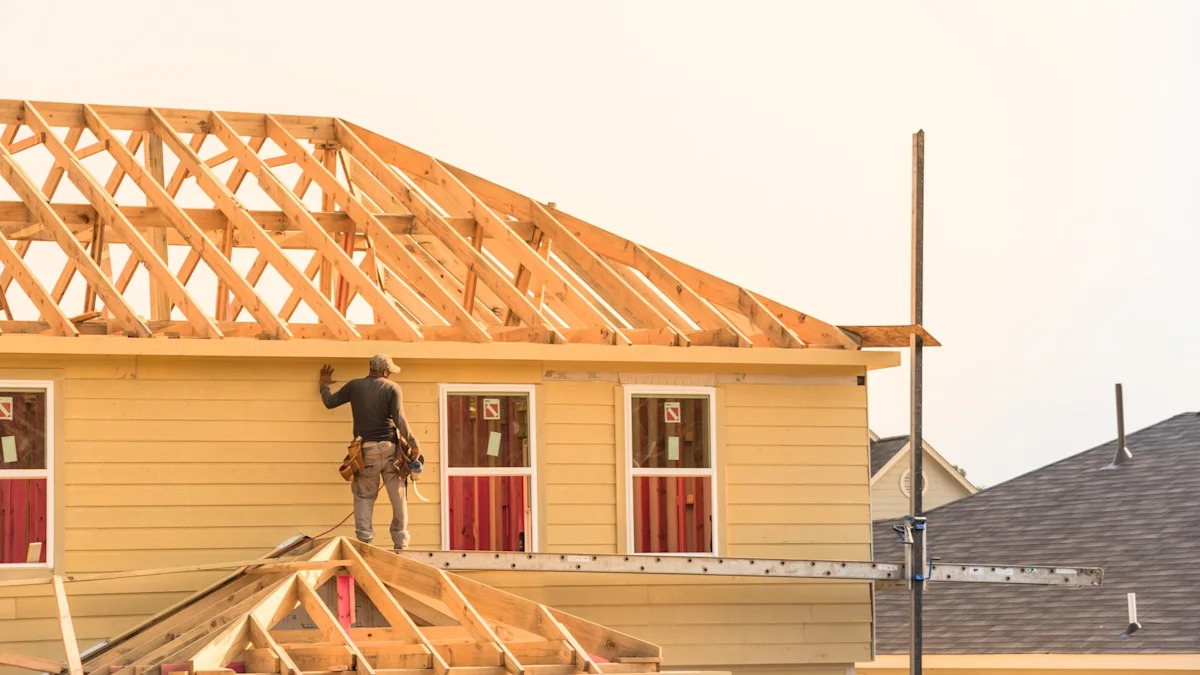
LGI Homes has opened Chisolm Park in Weatherford, Texas, a community of single family homes with six floor plans and CompleteHome Plus features included, with prices starting in the $300,000s.
The focus on value loaded entry level product in a growing Texas suburb highlights how LGI Homes is leaning into payment sensitive demand.
This article examines how LGI Homes’ investment narrative aligns with this new Texas community launch and the included CompleteHome features.
Scan how LGI Homes compares with other value focused builders by reviewing a curated set of list of solid balance sheet and fundamentals (25 results) that may also appeal to payment sensitive buyers.
LGI Homes Investment Narrative Recap
To own LGI Homes, you need to believe that its entry level focused model can translate housing undersupply and demographic demand into steady community openings and healthier profitability. The Chisolm Park launch fits that belief, but by itself looks incremental for near term results. The more immediate swing factor remains how quickly net orders and cancellations stabilize as buyers react to financing conditions.
The main short term catalyst is execution on the existing land pipeline while protecting margins that already sit at 3.9%, below last year. Affordability pressure, higher potential lumber tariffs and reliance on external borrowing still sit on the other side of the ledger, so new community openings help the story but do not remove those risks.
The recent Seventh Amendment to LGI Homes credit agreement is the announcement that ties closest to this growth push. Extending most revolving commitments out to 2030 and setting total capacity around US$1.166b, with an additional US$175m incremental facility, gives the builder room to fund more communities like Chisolm Park if it chooses to draw on that liquidity.
For you as an investor, that expanded facility cuts both ways. Longer dated access to capital can support the land heavy model that underpins future closings. At the same time, the existing concern that debt is not well covered by operating cash flow does not disappear. Execution now hinges on converting that borrowing capacity into profitable, not just higher volume, activity.
LGI Homes’ narrative projects US$2.5b revenue and US$117.1 million earnings by 2029. This assumes 14.8% yearly revenue growth and roughly a US$50.9 million earnings increase from the current US$66.2 million level.
Uncover why LGI Homes’ fair value indicates a 116% potential upside to its current price, which could narrow quickly.

Read More: Is New Texas Community Altering The Investment Case For LGI Homes (LGIH)?
